- What each one actually is
- Where the digital account wins
- Where the traditional bank wins
- One factor that decides on its own: being paid in cash
- What many people do instead: both
- How to check that your money is insured
- What happens when something goes wrong
- How each option affects your credit history
- Conclusion
- Official sources
Quick answer A neobank or digital account usually wins on fees: no monthly fee, no minimum balance and often no overdraft fee. A traditional bank wins if you get paid or deposit in cash, need a branch, or want loans and cards in one place. Many neobanks are not banks: your money is held by a partner bank, so check that it is FDIC-insured. Many people use both.
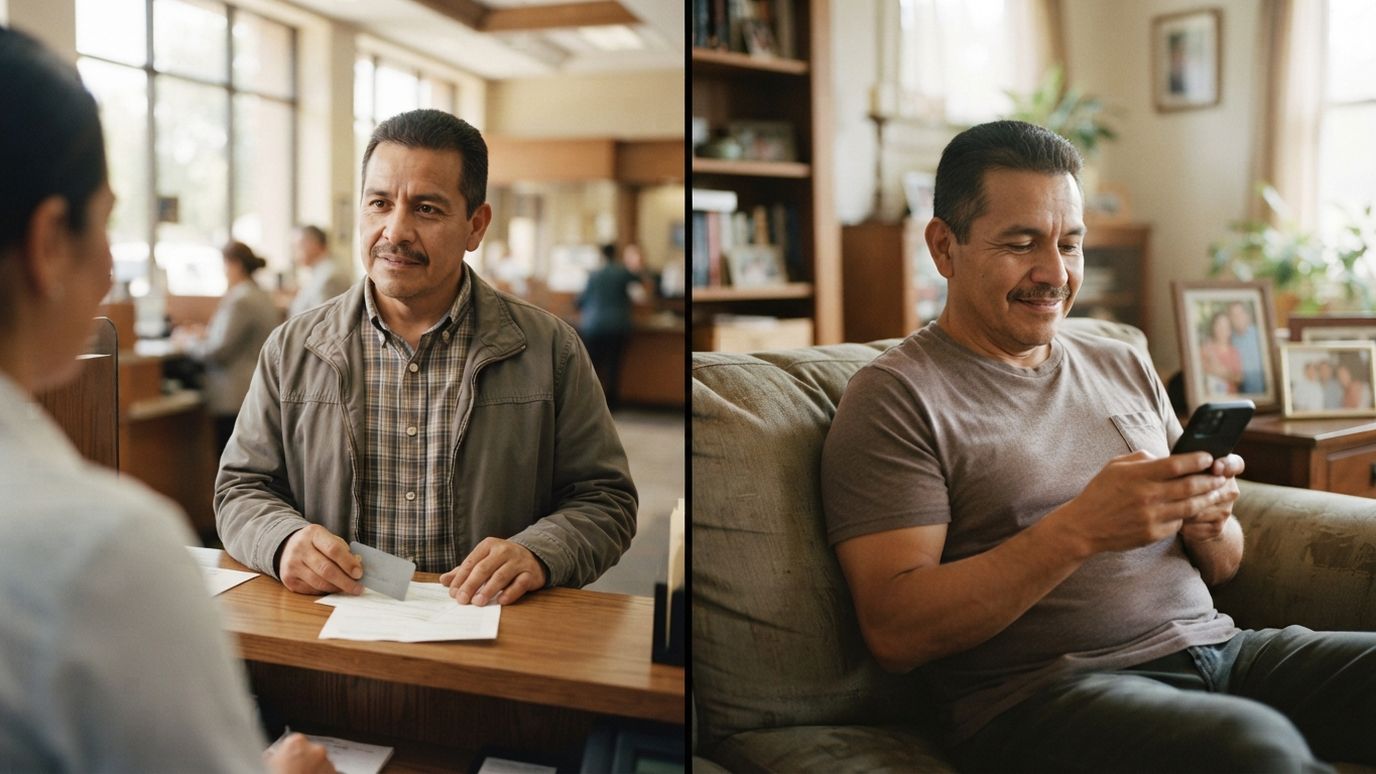
When the time comes to open an account in the United States, the decision is no longer just which bank, but which kind. On one side are the long-established banks, with their own branches and ATMs. On the other are digital accounts and neobanks, which run entirely from your phone and tend to advertise no fees.
Neither option is better in the abstract. What exists is a set of concrete trade-offs, and the right choice depends on how you get paid, how you spend, and what you need the bank to do for you.
What each one actually is
The traditional bank account
This is opened by a bank with its own banking charter, which holds your money, has a branch and ATM network, and offers the full range of products: accounts, cards, loans, mortgages, safe deposit boxes. Your deposit is insured directly by federal deposit insurance.
The digital account or neobank
Here comes a nuance almost nobody explains and that matters. Many neobanks are not banks: they are financial technology companies that provide the interface and the product, while the money is held at a chartered partner bank. Your money is usually insured just the same, but through that partner bank.
That structure works fine day to day, but it is worth knowing, because if a problem arises there are two entities involved instead of one and resolution can be slower.
Where the digital account wins
- Fees. No monthly fee, no minimum balance, and in many cases no overdraft fee. It is their main argument and it is real.
- Opening. Done in minutes from your phone, with no appointment and no trip.
- Early pay. Several release direct-deposited wages a couple of days ahead of the official date.
- Tools. Spending categorization, savings envelopes, real-time alerts, and instant card freezing from the app.
- Savings yield. With no branches to maintain, they usually offer considerably better rates on savings accounts.
Where the traditional bank wins
- Cash. Depositing bills is straightforward at a branch and difficult or impossible with many digital accounts. If part of your work is paid in cash, this alone settles the choice.
- Checks. Cashier’s checks, bank drafts, and certified checks are still needed to rent, buy a car, or close certain transactions.
- In-person service. When something goes seriously wrong, speaking to a person at a counter resolves in an afternoon what chat can drag out for weeks.
- Long-term relationship. A bank that has watched you get paid and save for years is far more flexible when you ask for a card or a loan.
- Documentation. Balance letters, stamped statements, and formal proofs are easier to obtain.
One factor that decides on its own: being paid in cash
This is the most decisive element and the one most people overlook. If part of your income arrives as bills, you need a way to deposit it. Digital accounts that allow it usually do so through networks of partner retailers that charge a fee per deposit, with monthly caps.
Depositing $400 in cash every two weeks through one of those networks can cost more per year than the monthly fee of the traditional bank you were trying to avoid. Do the maths before deciding.
What many people do instead: both
You do not have to choose. A combination that works well and costs little to maintain:
- An account at a local bank or credit union, to deposit cash, get cashier’s checks, and build a relationship with the institution.
- A digital account for daily life, purchases, and spending-control tools.
- A digital savings account, which usually pays considerably more interest than a traditional bank’s.
The only caution is not to spread your money until you lose track of it. Two checking accounts and one savings account is manageable; five different apps is not.
How to check that your money is insured
Before putting money into any platform, check on its own website who holds the funds and through which institution they are insured. A serious platform states this clearly, naming the partner bank. If that information appears nowhere, that alone is reason enough not to open the account.
What happens when something goes wrong
In everyday use the two options look very similar. The real difference shows up the day there is a problem, and it is worth knowing beforehand.
The most common case is a precautionary account freeze after a transaction the system considers suspicious. At a traditional bank you can walk into a branch with your ID and resolve it on the spot. On a digital platform you depend on the support channel, which may be a chat, a form, or an email, and the timelines are far less predictable.
The second case is a fraudulent charge. Here the legal protection is the same for both: if you report it in time, the account holder’s liability is limited by federal rules. What differs is how quickly the process moves and how easily you can reach someone with authority to decide.
The third, and the one that causes the most distress, is a unilateral account closure. It happens at both types of institution, but on digital platforms it usually arrives by email with no detailed explanation, leaving funds held for weeks while the review is completed. That is a strong reason not to keep all your money in one place, whatever type it is.
- Do not keep your only emergency fund on a platform with no in-person support.
- Keep a digital copy of your identity documents so you can respond quickly to any verification.
- Download your statements periodically rather than assuming they will always be available in the app.
How each option affects your credit history
One important clarification: neither a traditional checking account nor a digital one builds credit history on its own. Deposit accounts are not reported to the credit bureaus, so having held the same account for ten years does not appear on your report.
What does change is your access to the next step up. A bank or credit union that has been watching your income and behavior for a while can approve you for a secured card or a small loan on the strength of that internal information, even when the bureaus have nothing on you. That is a solid argument for opening an account at a local institution as early as possible, even if you then use a digital one day to day.
Some digital platforms do offer cards that report to the bureaus, and even services that add your rent or utility payments to your report. These are useful, but it is worth reading carefully what exactly they report and to which bureaus, because the differences between products are large.
Conclusion
If you are paid by direct deposit, spend by card, and value paying no fees, a digital account will probably serve you better. If you handle cash, need cashier’s checks, or want to build a banking relationship ahead of applying for credit, the traditional bank remains irreplaceable. And if your situation has a bit of both, having one of each is the most sensible answer.
Related articles
Official sources
To check what this guide explains, these are the official references. If a rule changes, the official version always prevails.
- FDIC: deposit insurance: which accounts are insured and up to what amount.
- CFPB: credit cards: official guidance on card fees, interest and your rights.
