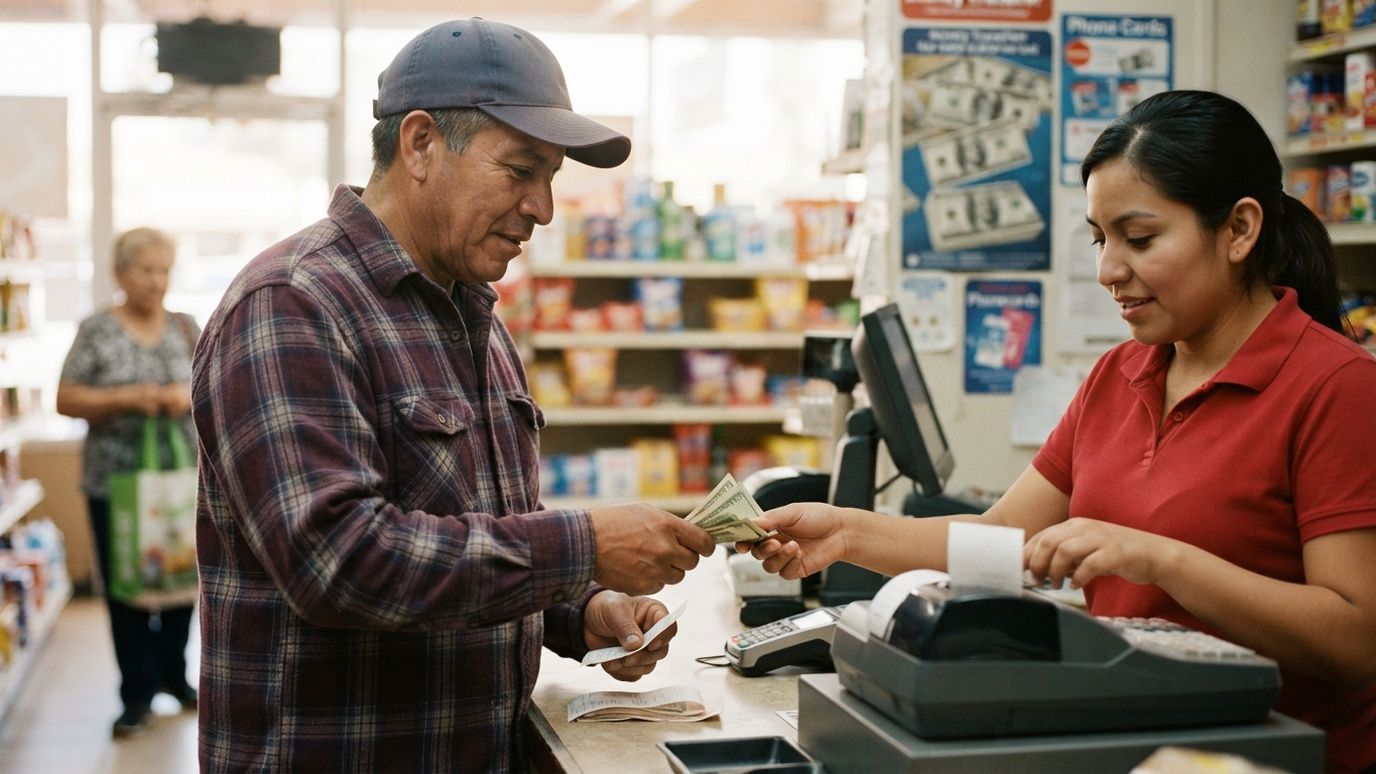
Quick answer Since January 1, 2026, a federal 1% tax applies to money sent abroad when the transfer is paid with cash, a money order or a cashier’s check. The provider collects it at the time of sending. It does not depend on the destination country or your immigration status, only on how you pay. If you pay from a bank account or with a debit card, it does not apply. On a $500 cash transfer, it adds $5.
Since January 1, 2026, a 1% federal tax has been in effect in the United States on certain money transfers sent abroad. The news caused considerable alarm while it was being debated, partly because the early versions of the bill were far harsher than the one that was ultimately enacted. This article explains what the rule actually says as it stands, who it really affects, and what you can do so that it does not apply to you.
This content is informational and is not tax advice. For your specific situation, consult official IRS guidance or a professional.
What the tax actually taxes
The tax is a 1% levy on the amount of the transfer. It does not replace the provider’s fee or the exchange rate margin: it is added on top of them.
The key point, and the one most people are unaware of, is that what determines whether it applies to you is not where you send or who you are, but how you pay for the transfer. The tax falls on transfers funded with cash, money orders, cashier’s checks, and other similar physical instruments.
The tax is collected by the transfer provider itself, which withholds it at the time of the transfer and remits it to the government. In other words, you do not have to report it separately: you will see it in the transaction breakdown.
Which transfers fall outside it
Here is the practical part. Under the enacted rule, a transfer is not subject to the tax when it is funded from:
- A bank or credit union account held at a US institution.
- A debit card issued in the United States.
- A credit card issued in the United States.
Put another way: if you send money from your account or with your card, the 1% tax should not apply. If you walk up to a counter with bills and pay in cash, it does.
One important warning about credit cards: even though they fall outside the tax, they remain the worst way to pay for a transfer, because many issuers treat it as a cash advance, with its own fee, a higher interest rate, and no grace period. Avoiding 1% in order to pay 5% is not a good trade.
Who it affects by immigration status
One of the biggest sources of confusion in the public debate comes from here. Early versions of the bill proposed a much larger tax aimed specifically at people who were not US citizens, which would have required providers to verify each customer’s citizenship.
To see how much actually arrives with each provider, use the real cost of a remittance calculator.
The version that was finally enacted dropped that approach. The tax applies based on the payment method, not on the sender’s immigration status or nationality. A US citizen paying in cash is subject to it just like anyone else; someone without status paying from their bank account is not.
What it amounts to in practice
In relative terms, 1% is small compared with what many senders pay without noticing in the exchange rate margin. Some examples:
- A $200 cash transfer: $2 in tax.
- A $500 cash transfer: $5.
- A $1,000 cash transfer: $10.
For someone sending $300 every two weeks in cash, that comes to roughly $78 a year. That is real money, and it is avoidable simply by changing how you pay.
For context: a provider applying a 3% exchange rate margin costs three times more than this tax, and almost nobody looks at it.
How to avoid it, legally and simply
No manoeuvring is required: you just change the payment method. If you have been paying in cash, the alternative is to fund the transfer from a US bank account.
If you do not have an account, opening one is easier than many people think: there are banks and credit unions that accept an ITIN, a foreign passport, or a consular ID instead of a Social Security number. Beyond avoiding the 1%, paying from an account usually gets you lower fees and a better exchange rate than paying at a counter, so the saving is twofold.
- Open an account at a bank or credit union that accepts your documentation.
- Link it to the transfer app you use.
- Fund transfers from the account instead of with cash.
- Keep the breakdown of the first transaction to confirm the tax is not being applied.
What to check in your transfer breakdown
Providers are required to show you the total cost before you confirm the transaction. From now on it is worth reviewing three lines instead of one: the fee, the exchange rate applied, and, if you pay in cash, the 1% tax.
If you pay from a bank account and still see a 1% charge in the breakdown, ask the provider before confirming. It may be a misclassification of the payment method, and it is easier to sort out beforehand than to claim back afterwards.
Official sources
To check what this guide explains, these are the official references. If a rule changes, the official version always prevails.
- IRS: remittance transfer tax: the official notice on the 1% tax in force since 2026.
- CFPB: what is a remittance transfer and what are my rights: required disclosures, 30 minutes to cancel and 180 days to report errors.
Frequently asked questions
Does it affect transfers within the United States?
No. The tax concerns money transfers sent abroad through a transfer service provider.
Does it also apply to cryptocurrency?
The rule is written around remittance transfer providers. How other vehicles are treated may depend on interpretation and on guidance the IRS publishes, so it is best not to assume anything and to check official information.
Can I recover the tax on my return?
There is a credit route for certain taxpayers, but it depends on your specific tax situation. This is exactly the kind of question to put to a professional rather than settle by intuition.
How providers are applying it
The rule is the same for everyone, but the way it is displayed is not. Some services break the tax out on its own line; others fold it into the total and only itemize it if you expand the summary. If you pay in cash and see no reference to the tax, do not assume you are not being charged it: ask for the full breakdown.
There are also differences in how certain intermediate payment methods are classified, such as prepaid cards loaded with cash or wallet balances topped up at a counter. If you use one of these, ask explicitly how your provider treats it before making a large transfer.
Keep the receipts from your first transfers after the change. If you later find the tax was applied while paying from a bank account, that document is what supports your claim.
Conclusion
The 1% tax on cash remittances is real, but far narrower than was feared during the debate: it does not depend on your nationality or your status, but on how you pay. Funding your transfers from a US bank account avoids it entirely and, incidentally, usually makes the transfer cheaper in other ways too. If you still pay in cash out of habit, this is a good reason to take the step of opening an account.
Related articles
