- The requirements that always apply
- SSN or ITIN: the question that comes up most
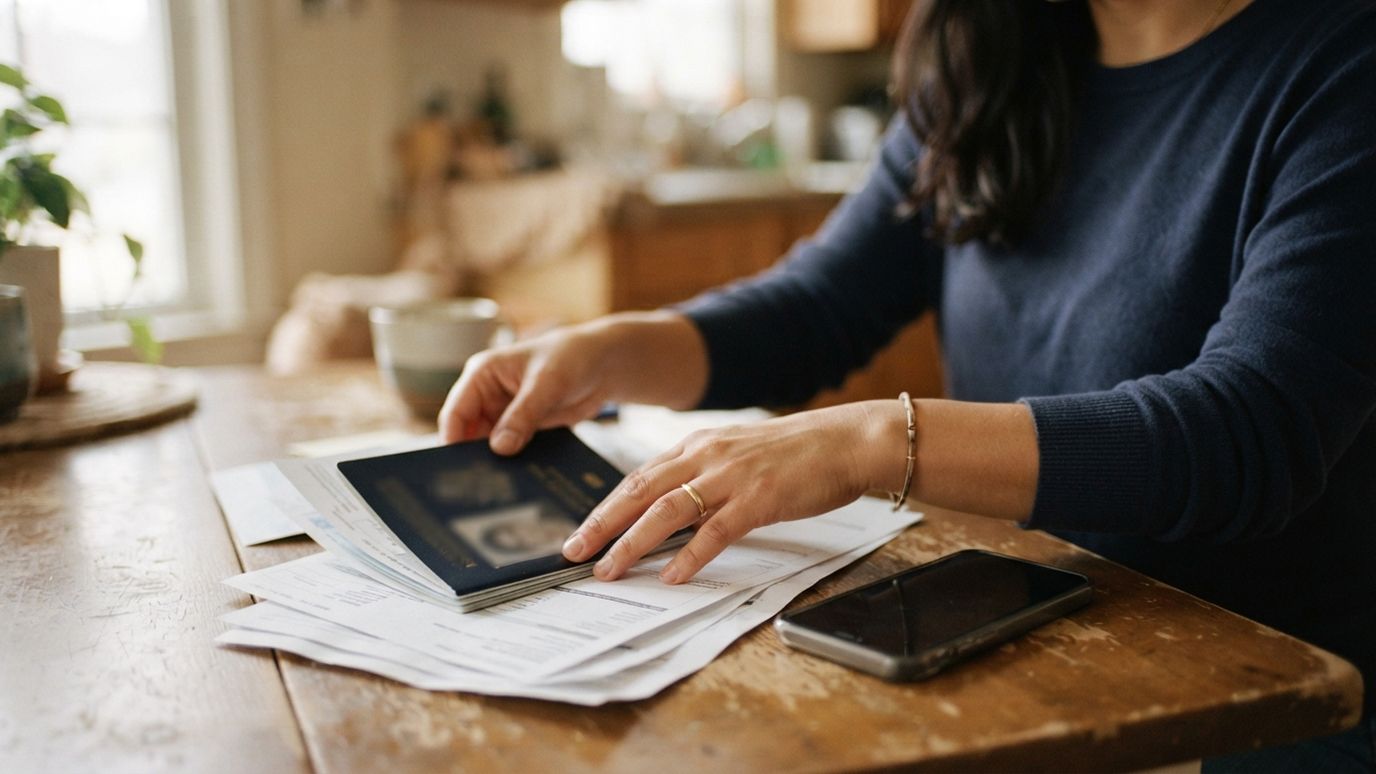
- What documents they will ask for
- Income: what you can actually report
- Credit history: the requirement you cannot meet on day one
- How to know if you will be approved before applying
- Mistakes that cost you an approval
- Conclusion
- Official sources
Quick answer To apply for a US credit card you need to be at least 18, have an SSN or ITIN, a US address and income you can state (you must be 21, or show independent income or a co-signer, if you are younger). If the issuer asks to verify, it will request a photo ID, proof of address and sometimes proof of income such as pay stubs or a tax return. With no credit history, expect to start with a secured card.
Before filling out a credit card application it helps to know what the bank will actually look at, because most people focus on what matters least. You do not need a high income or years in the country. You need to meet a few specific requirements and, above all, pick the right product for your situation.
This guide covers the real requirements for a US credit card application, what can be substituted and what cannot, and how to find out in advance whether you will be approved.
The requirements that always apply
- Being 18 or older. Under 21, the law also requires proof of sufficient independent income or a co-signer of legal age.
- A physical US address. A PO box will not do for most issuers. It can be where you live, even if the lease is not in your name.
- A taxpayer identification number. This is the sticking point for many people, and it deserves its own section.
- Reportable income. There is no legal minimum; each issuer sets its own and many do not publish the figure.
Note what is not on the list: you do not need to be a citizen, a permanent resident, or to have been in the country for a minimum period.
SSN or ITIN: the question that comes up most
The short answer: a Social Security number is not required at every bank, even though it is what they ask for by default.
- With an SSN you have access to practically the whole market.
- With an ITIN (the taxpayer identification number issued by the IRS) you can apply at a growing number of institutions. These tend to be credit unions, banks with programs for immigrant communities, and a few specific national issuers.
- With neither the normal route closes, but there are products tied to a bank account with a security deposit that sometimes accept a passport and consular ID.
If you do not have an SSN, do not waste applications on large banks that will not accept an ITIN: every decline leaves a hard inquiry on your file. Ask before applying whether they accept ITIN, by phone or in branch.
What documents they will ask for
The application itself is usually done online in ten minutes. What they may ask for afterwards, to verify:
- Photo ID: passport, state driver’s license, state ID card or consular ID, depending on the issuer.
- Taxpayer ID: SSN or ITIN.
- Proof of address: a utility bill, a lease, or a recent bank statement in your name showing your address.
- Proof of income: pay stubs, a tax return or bank statements. They do not always ask up front, but they will if something does not add up.
Have everything scanned before you start. A verification that stalls because you cannot find a document can end in a decline for “unable to verify identity”.
Income: what you can actually report
This field gets filled in wrong very often, and against your own interest.
Regulation lets you report the income you have reasonable access to, not only your paycheck. Depending on your situation, that can include:
- Your gross salary, before taxes and deductions.
- Self-employment income or part-time work.
- If you are 21 or older, your spouse’s or partner’s income that you have reasonable access to.
- Pensions, benefits, scholarships and other regular income.
Do not inflate the figure: it is information you are signing for and they can verify it. But do not leave it short either because you did not know what counted.
On minimums: most issuers do not publish an amount. What they do look at is the ratio between your debt and your income. Applications get approved every day on modest incomes with low debt.
Credit history: the requirement you cannot meet on day one
It is the most common reason for declines among newcomers, and it does not mean you look bad: it means you do not exist in the system yet.
If that is you, do not apply for a regular card. Start with one of these three doors:
- Secured card. You leave a deposit that becomes your limit. The bank risks very little, so it is easier to get approved with no history, though it still checks your identity and income. It reports to the bureaus like any other card.
- Authorized user. A family member adds you to their card. Their history on that account starts appearing on your report. It is the fastest route and requires no application of your own.
- Credit builder loan. Offered mainly by credit unions: you make payments that are returned to you at the end, and each payment builds history.
With any of the three, in six months you will have enough of a file for a regular card to consider you.
How to know if you will be approved before applying
This is what saves the most inquiries and almost nobody uses it:
- Pre-qualification tools. Almost every large issuer has a form that tells you which cards you have a chance at. It uses a soft inquiry: it does not affect your score.
- Pre-qualified is not pre-approved. It is good guidance, not a guarantee. The formal application still makes a hard inquiry.
- Ask at your own bank. If you already have an account with them, they can see your deposit history and tend to be more flexible than with a stranger.
Mistakes that cost you an approval
- Applying at several banks the same day. Each leaves its inquiry and the set of them counts against you.
- Applying for a premium card with no history. High-rewards cards expect established profiles. Start with the same issuer’s basic card.
- Writing your name differently from your ID. With two surnames, enter exactly what appears on your identification.
- Leaving income blank or entering only your paycheck when you could report more.
- Not checking your report first. If there is an error, you fix it for free and apply afterwards.
Conclusion
The requirements for an application are few and concrete: 18 years old, a US address, a taxpayer ID and reportable income. No citizenship, no residency.
What really decides it is credit history, and if you do not have it the answer is not more applications but starting with a secured card or as an authorized user. And before any application, run the pre-qualification: it is free and costs you no points.
This guide is informational and does not replace personalized financial advice. Specific requirements vary by institution: confirm them directly with the issuer before applying.
Related articles
Official sources
To check what this guide explains, these are the official references. If a rule changes, the official version always prevails.
- CFPB: credit cards: official guidance on card fees, interest and your rights.
- CFPB: credit reports and scores: what is in your report, how scores are used and how to dispute errors.
